‏إظهار الرسائل ذات التسميات Loan. إظهار كافة الرسائل

Modi Govt To Roll Out ₹2.5 Lakh Crore Lifeline for War-Hit Businesses

Modi Govt To Roll Out ₹2.5 Lakh Crore Lifeline for War-Hit Businesses

India is reportedly preparing a massive ₹2.5 lakh crore ($26.7 billion) sovereign guarantee scheme to protect businesses hit by the Iran war, offering up to 90% credit guarantees on loans for four years. This move is aimed at shielding small and medium enterprises (SMEs), especially in sectors like textiles and glass, from supply chain shocks and rising inflation.

A sovereign guarantee (or government guarantee) is a formal assurance by the national government that it will take responsibility for a borrower’s debt if they fail to repay. In India’s case, it means the government will backstop loans to businesses hit by the Iran war, ensuring banks feel secure in lending.

Amid Iran War, supply chains from West Asia are strained, hitting raw material imports. Smaller firms in textiles, glass, and other sectors face bankruptcy risks. Moreover, rising crude prices threaten inflation and growth.  By offering sovereign guarantees, India ensures businesses can still access loans despite heightened risks.  

Key Details 

  • Loan Coverage: Up to ₹100 crore ($10.75 million) per borrower
  • Guarantee Extent: 90% sovereign guarantee to lenders in case of default
  • Total Package Size: ₹2.5 lakh crore ($26.7 billion)
  • Duration: Valid for four years, modeled on the COVID-era ECLGS
  • Target Sectors: SMEs in textiles and glass manufacturing

Context: Why This Matters

  • Iran War Impact: Disrupted supply chains across West Asia
  • Oil Dependency: India faces risks of inflation and slower growth
  • Economic Stability: Designed to prevent bankruptcies and stabilize industries

Comparison with COVID-Era Credit Scheme

Feature COVID ECLGS (2020) Iran War Guarantee (2026)
Package Size ₹3 lakh crore ₹2.5 lakh crore
Guarantee Coverage 100% for small loans 90% up to ₹100 crore
Duration 4 years 4 years
Target MSMEs across sectors SMEs in war-hit supply chains

Risks & Trade-Offs

  • Fiscal Burden: Estimated cost of ₹170–180 billion
  • Inflation Pressure: Rising oil prices could offset benefits
  • Banking Sector Exposure: Liquidity stress possible if defaults surge
  • Global Uncertainty: Escalation may worsen disruptions

What This Means for Businesses

  • Immediate Relief: Easier access to loans with reduced risk
  • Strategic Planning: Prepare for higher input costs and delays
  • Opportunity: Government backing may encourage more lending

Global Context: Sovereign Guarantee Schemes vs Other Crisis Tools

India’s sovereign guarantee scheme can be better understood when compared with how other countries respond to crises.

Global Comparisons

Country Tool Used Purpose Example
India Sovereign loan guarantees Protect SMEs from war-driven supply shocks ₹2.5 lakh crore guarantee for Iran war-hit firms
United States Direct stimulus + Fed liquidity Boost demand and stabilize banks CARES Act (2020) gave direct cash + Fed backstops
European Union Loan guarantees via European Investment Bank Support cross-border firms and maintain credit flow EU COVID Guarantee Fund (2020) covered €200 billion
Japan Government-backed credit insurance Shield exporters from global shocks Trade insurance for firms during supply chain crises
China State-directed lending + subsidies Keep industries afloat and maintain employment State banks extend cheap loans with gov’t backing

Key Differences

  • India: Uses sovereign guarantees to encourage banks to lend.
  • US: Relies on direct cash transfers and liquidity injections.
  • EU: Pooled guarantees at a supranational level.
  • Japan & China: Insurance and state-directed lending, reflecting centralized structures.

Why Guarantees Matter

  • Cheaper for government upfront than direct subsidies
  • Boosts confidence in banking sector
  • Provides targeted relief for vulnerable industries
  • Risk shifts to government balance sheet if defaults surge. 


India’s sovereign guarantee scheme is a shield, not a cash injection. It ensures SMEs can still borrow during the Iran war crisis, but unlike the US or EU, it doesn’t directly hand out money—it leverages the government’s credibility to keep credit flowing.

Quick Personal Loan vs Traditional Loan: Which Saves More Time?

Quick Personal Loan vs Traditional Loan: Which Saves More Time?

Time is often more valuable than money, especially when unexpected expenses pop up. From sudden medical bills and urgent home repairs to last-minute travel, there are moments when immediate financial support becomes essential. In such situations, choosing between a quick personal loan and a traditional loan can make a significant difference. While both options provide access to funds, the speed, convenience, and ease of application can vary greatly.

A quick personal loan is designed for fast approval and rapid disbursement of funds, whereas traditional loans typically involve longer processing time and more paperwork. Understanding these differences is crucial to determining which option can truly save you time and efficiently meet your urgent financial needs.

Understanding Quick Personal Loans

A quick personal loan is designed to provide fast access to funds with minimal paperwork. Unlike traditional loans, these loans are often processed digitally, allowing applicants to receive approval within hours or a few business days. Financial institutions and fintech companies have developed these loans to cater to urgent financial needs, providing a convenient solution for borrowers who cannot afford to wait.

The key benefit of a quick personal loan is its streamlined process. Typically, all you need is basic personal and financial information, and sometimes your bank account details for verification. This simplicity translates into faster disbursement of funds, often directly into your account, helping you address your needs without delay.

How Traditional Loans Work

On the other hand, traditional loans follow a more structured and often slower approval process. These loans usually involve a thorough assessment of your creditworthiness, income verification, and other documentation. While this approach ensures a detailed evaluation and potentially lower interest rates, it can take anywhere from a few days to several weeks before funds are released.

The lengthier process can be inconvenient if you are facing urgent financial requirements. Though traditional loans are reliable and often suited for planned expenses, they may not be the best choice when time is of the essence.

Application Process: Speed vs Thoroughness

When comparing a quick personal loan to a traditional loan, the application process is a major differentiator. Quick personal loans often allow you to apply online, eliminating the need to visit a bank branch. Verification and approval are expedited using automated systems, which means you can receive funds within 24-48 hours.

In contrast, traditional loans may require in-person visits, multiple forms, and detailed documentation. While this thoroughness ensures that the lender fully assesses the risk, it significantly increases the waiting period. If your primary goal is speed, a quick personal loan clearly has the edge.

Documentation and Eligibility Requirements

One of the reasons quick personal loans are faster is the simplified documentation process. Most lenders require only a government-issued ID, proof of income, and bank account details. Some fintech lenders even offer instant approval with minimal paperwork, making the process highly efficient.

Traditional loans, however, involve more extensive documentation. In addition to identification and income proof, you may need credit reports, tax returns, employment verification, and collateral documents for secured loans. While this thorough evaluation can result in better loan terms, it significantly delays access to funds.

Approval Time and Fund Disbursement

Time is money, and in financial emergencies, waiting days or weeks can exacerbate stress. A quick personal loan often provides approval in as little as a few hours, with funds transferred within a day. This rapid turnaround makes it an ideal option for urgent needs.

Traditional loans, in contrast, can take weeks for approval and fund disbursement. While they may offer lower interest rates or higher loan amounts, the extended timeline can be inconvenient for borrowers requiring immediate support.

Interest Rates and Cost Considerations

While speed is a major advantage of quick personal loans, it’s essential to consider costs. These loans may have slightly higher interest rates compared to traditional loans due to the expedited process and lower risk assessment time. However, the trade-off is the convenience and time saved.

Traditional loans often provide lower interest rates, particularly for borrowers with good credit scores. But if time is critical, the slightly higher cost of a quick personal loan may be justified, especially when it prevents financial setbacks or late fees on urgent bills.

Flexibility and Convenience

Flexibility is another area where quick personal loans shine. Many lenders offer online applications, digital agreements, and 24/7 access, allowing you to manage your loan from anywhere. This convenience ensures that you don’t have to wait for bank hours or schedule appointments.

Traditional loans, while reliable, often lack this level of convenience. You may need to follow up with bank representatives, submit physical documents, and adhere to strict schedules, which can add to the overall time spent securing funds.

Which Saves More Time?

When it comes to saving time, a quick personal loan stands out against traditional loans. With its simplified application, minimal paperwork, rapid approval, and instant digital disbursement, it’s ideal for urgent financial needs. Traditional loans, though often cheaper and more structured, usually involve longer processing times and are better suited for planned expenses.

In situations where every hour matters, a quick personal loan can help you manage emergencies effectively, avoid late fees, and maintain stability. While cost plays a role, the time and convenience offered often outweigh slightly higher interest rates. The choice ultimately depends on whether you prioritize speed or long-term savings. For those seeking faster solutions, platforms like Olyv make the process smoother than ever.

ADB Approves $350 Mn Loan to Enhance India’s Logistics Sector and Export Competitiveness

ADB Approves $350 Mn Loan to Enhance India’s Logistics Sector and Export Competitiveness

The Asian Development Bank (ADB) has approved a $350 million policy-based loan to support India in strengthening and modernizing its logistics sector. This funding will finance the second subprogram under the Strengthening Multimodal and Integrated Logistics Ecosystem Program. The goal is to create a comprehensive policy, planning, and institutional framework at the state and city levels.

Key Objectives
  • Implementing strategic policy reforms to improve infrastructure and streamline logistics processes.
  • Promoting the integration of digital technologies to facilitate smoother movement of goods.
  • Advancing green transition guidelines for inland waterways and promoting environmentally sustainable logistics practices.
  • Creating substantial employment opportunities across urban and rural regions.
The ADB's support aligns with the Indian government's initiatives like the Prime Minister Gati Shakti-National Master Plan (PMGS-NMP) and the National Logistics Policy (NLP), aiming to modernize infrastructure and promote digitization.

"The development of the logistics sector has a profound impact on the manufacturing sector's competitiveness. Improved logistics efficiency enhances supply chain resilience, reduces transaction costs, and boosts export competitiveness,” said ADB Senior Public Management Economist Sameer Khatiwada. “The integration of digital technologies and standardized processes facilitates smoother movement of goods, which is crucial for manufacturing growth.”

The Advantages of Unsecured Business Loans for Women-Owned Businesses

The Advantages of Unsecured Business Loans for Women-Owned Businesses

In today's dynamic business landscape, women entrepreneurs are making remarkable strides, bringing innovation, creativity, and leadership to the forefront. To empower and support the growth of women-owned businesses, these loans provide a range of advantages. This includes competitive Business Loan interest rates, flexible repayment terms, and simplified application processes. In this article, we will explore the advantages of Unsecured Business Loans for women-owned businesses and how they can fuel their success.

Advantages of Unsecured Business Loans for Women Entrepreneurs

Easy Access to Funding

One of the primary advantages of Unsecured Business Loans for women-owned businesses is easy access to funding. Unlike Secured Loans that require collateral, Unsecured Loans do not necessitate the pledging of assets, making the loan application process simpler and faster. Women entrepreneurs can swiftly obtain the funds they need to start a new venture, expand an existing business, or invest in technology and equipment.

Financial Independence

Unsecured Business Loans provide women entrepreneurs with the opportunity to achieve financial independence. By accessing capital without the requirement of collateral, women-owned businesses can retain ownership of their assets and maintain control over their business decisions. This independence allows women entrepreneurs to pursue their vision and make strategic choices without compromising their business's long-term growth.

Tailored Loan Amounts

Unsecured Business Loans offer flexibility in loan amounts, allowing women-owned businesses to access the capital required for various purposes. Whether it's expanding operations, purchasing inventory, investing in technology, or marketing initiatives, Unsecured Business Loans can be tailored to meet specific business needs. This enables women entrepreneurs to seize growth opportunities and stay competitive in their respective industries.

Competitive Interest Rates

Financial institutions understand the importance of providing access to capital at favorable terms for women-owned businesses. As a result, Unsecured Business Loans often come with competitive Business Loan interest rates, making the borrowing process affordable and cost-effective. Lower interest rates enable women entrepreneurs to manage their finances more effectively, improve profitability, and invest in sustainable growth strategies. Women-owned businesses can leverage these competitive Business Loan interest rates to maximize their return on investment.

Shorter Loan Terms

Unsecured Loans often have shorter repayment periods compared to Secured Loans. This is because lenders try to mitigate their risk by limiting the time during which the borrower has to repay the loan.

Networking and Support

Many financial institutions that offer Unsecured Business Loans for women entrepreneurs also provide networking opportunities, mentoring programs, and support services specifically designed to assist women-owned businesses. These additional resources can offer valuable guidance, connections to potential customers or investors, and access to industry-specific expertise, further boosting the chances of success for women entrepreneurs.

Quick and Convenient Application Process

Financial institutions, such as NBFCs, understand the value of time for women entrepreneurs. The application process for Unsecured Business Loans is streamlined, making it quick and convenient. These institutions prioritize efficiency and aim to minimize the time and effort required for loan approval and disbursal.

Flexible Loan Amounts

Unsecured Business Loans offer flexibility in loan amounts, allowing women-owned businesses to access the capital required for various purposes. Whether it's expanding operations, purchasing inventory, investing in technology, or marketing initiatives, Unsecured Business Loans can be tailored to meet specific business needs.

Business Expansion and Growth

Unsecured Business Loans provide women-owned businesses with the financial boost needed to expand operations and foster growth. Whether it's opening new locations, hiring additional staff, or investing in marketing and advertising campaigns, these loans offer the necessary capital to fuel expansion plans.

Enhanced Cash Flow Management

Maintaining a healthy cash flow is vital for any business's success, and Unsecured Business Loans can play a pivotal role in achieving this. Women-owned businesses often face challenges in managing cash flow due to factors such as delayed payments or seasonal fluctuations. Unsecured Business Loans provide the necessary liquidity to bridge these gaps, ensuring a steady cash flow and enabling businesses to meet their financial obligations promptly.

Conclusion

Unsecured Business Loans have emerged as a game-changer for women-owned businesses, providing them with the financial support they need to thrive and succeed in today's competitive business environment. The advantages of easy access to funding, financial independence, tailored loan amounts, competitive Business Loan interest rates, business expansion opportunities, enhanced cash flow management, building credit history, and networking support contribute significantly to the growth and success of women entrepreneurs. By leveraging these advantages and accessing Unsecured Business Loans, women-owned businesses can unlock their full potential, drive innovation, and contribute to economic empowerment and gender equality in the business world. 


How a Bike Loan can Help You Purchase your Dream Bike

How a Bike Loan can Help You Purchase your Dream Bike

Bikes have emerged as a definitive answer to navigating traffic in India. Two-wheelers are also easy to use and are relatively inexpensive. This has increased the demand for bikes and two-wheelers in the Indian market.

As the demand for bikes continues to grow, so has the demand for bike loans. In order to meet this demand, financial institutions have fine tuned their bike loan offerings. These days, you can apply for a bike loan from the comfort of your home with minimal documentation.

Let’s take a closer look at bike loans and why they might be a great way to finance your bike purchase.

Why Choose Bike Loans?

1. Purchase your dream bike

Purchasing your bike in cash can be a little challenging as you’d have to make the entire payment at one go. This can deplete your savings and can cause some financial stress.

Apart from depleting your savings, paying for your bike out of pocket can also mean that you’d need to make some compromises. This can mean that you’d have to choose a more inexpensive variant or a different bike altogether. This may not be such a good idea, particularly if you plan on using your bike for the foreseeable future. A bike loan can help you purchase your preferred bike without any hassles.

A bike loan allows you to purchase the bike of your choice without having to make any compromises. With a bike loan, you just need to make a down payment of anywhere between 0% to 30% of your bike’s value and you’re good to go. Post this, all you have to do is make monthly payments towards your bike loan.

2. Helps plan finances better

Taking a bike loan ensures that your EMIs are spread evenly throughout the loan repayment tenure. Paying for the bike in one go can throw off your finances and can cause a lot of liquidity crunch. Instead, you can take advantage of a bike loan and allocate your funds towards building an emergency fund or investing.

Additionally, you can analyse your finances before taking a bike loan to understand your repayment capability. It’s impossible to take a one-size-fits-all approach to personal finance. This is why you should always take into account your unique life and financial circumstances to arrive at a repayment plan that works for you.

You can use a two wheeler EMI calculator to understand how loan amount, interest rates and loan repayment tenure affect your monthly payments. You can tweak the repayment tenure and the loan amount a little bit to help you arrive at an ideal EMI amount.

3. Rewards and offers

Nowadays, the loan industry has become quite competitive. This means that lenders are eager to give loans to credible borrowers. This has translated into lower interest rates, rewards, free insurance offers, additional discounts, full-financing with zero down payment, etc.

If you have a regular source of income and have a good credit score, you may be eligible for one or many of these offers. Taking advantage of these offers can help you make the most of your bike loan and lower costs.

4. Helps improve your credit score

If you are new to credit, one of the simplest ways to improve your credit score is to take a small ticket loan. Apart from being a small ticket loan that’s accessible, a bike loan is also a secured loan. This means that the interest rate on a bike loan is much lower than the interest rates offered on other small ticket unsecured loans.

A combination of accessibility and affordability makes bike loans a great way to enhance your credit score. If you’re planning to take a bike loan to improve your credit score, here are some things to keep in mind:
  • Avoid applying for multiple bike loans in a short period of time. This will signal to credit bureaus that you are desperate for credit and they may flag you as a risky borrower. This can lower your credit score.
  • Always make sure to pay your dues in full, on time. Defaulting on payments can negatively affect your credit score.

5. Easy application process

These days, applying for a bike loan is very simple and takes only a matter of minutes. You only need a few basic documents and information to get started. You can get started online through your preferred partner’s online portal.

6. Low interest rates

Being a small ticket secured loan, bike loans bear some of the lowest interest rates available in the market. You can take advantage of these low interest rates to fund your bike purchase. Bike loan interest rates can range anywhere from 6.85% to 28.30% per annum.

By shopping around a little bit and/or negotiating with your lending partner, you can get very low interest rates that can make your bike purchases quite affordable.

7. Tax benefits

If you’re a self-employed person and intend on using your bike for business purposes, then you can get tax benefits on your bike loan. The interest paid towards this bike loan will be considered a tax-deductible. Apart from this, you can also deduct the amount paid towards the maintenance of the vehicle from your profits while filing for taxes.

PAISALO and UCO Bank to Enable AGRI and Allied AGRI with Small Ticket Size Income Generation Loans

PAISALO and UCO Bank to Enable AGRI and Allied AGRI with Small Ticket Size Income Generation Loans

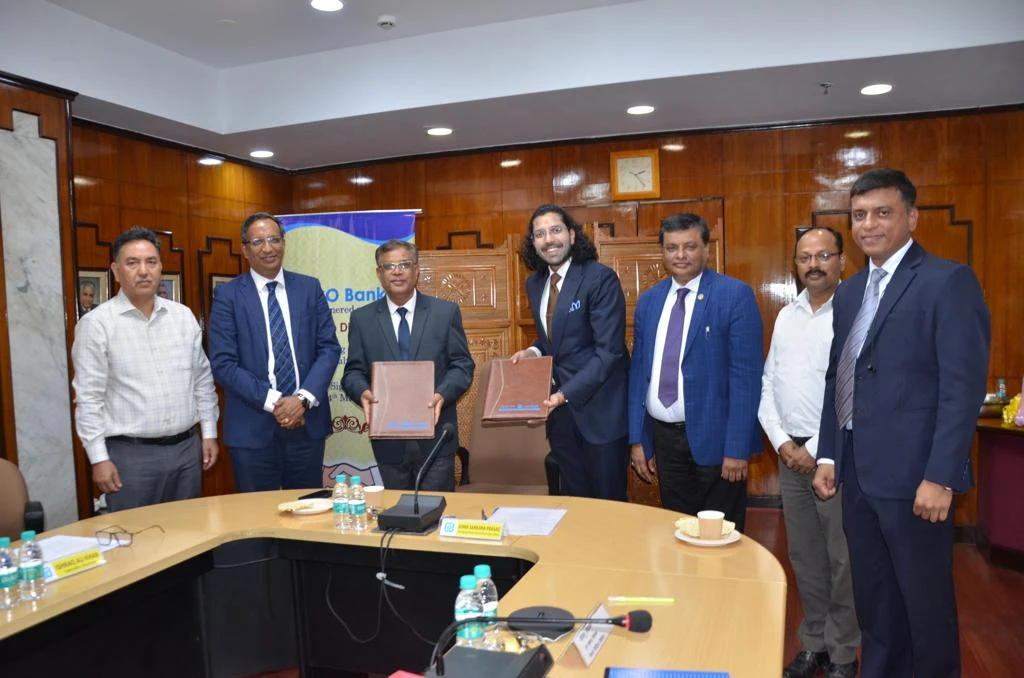
In recent years, AGRI and Allied AGRI have come out and blossomed to become great leaders and have set new heights of growth and progress for society in general. There still is a lot of room for growth and success for this very talented population. With the right amount of support, we can aim to have many AGRI, Allied AGRI, and women leaders in the near future. To contribute to this vision of empowering the AGRI and Allied AGRI, Paisalo Digital Limited signed a co-lending loan agreement with the UCO Bank today. This agreement is in conformity with the latest RBI circular on co-lending of loans as released on 05 November 2020.

UCO Bank-Paisalo's co-lending platform will leverage UCO Bank’s low cost of funds on the liability side and Paisalo’s origination, rule engine, and underwriting capabilities on the asset side, with the help of Paisalo’s digital platform for sourcing, servicing and recovery of these income generation priority sector loans.
 

Santanu Agarwal, Deputy Managing Director, Paisalo Digital Limited says, “Paisalo sees a huge opportunity and is well-positioned to capitalize on the huge Rs. 8 lakh crore market of small-ticket loans for our 365 million underbanked and under-serviced population. UCO Bank and Paisalo co-lending product is a big step towards Paisalo’s goal of creating the most competitive and seamless banking solution for India's Bottom of Pyramid Population.”

Speaking on the occasion Mr. Soma Sankara Prasad, MD & CEO of UCO Bank says, “co-lending arrangement is one of the new avenues of lending. The tie-up will give a boost to the agriculture advance of the Bank and it is a win-win situation for the bank as well as NBFC with benefit reaching to those at the bottom of the society.”

Executive Director Ishraq Ali Khan expressed that this is a great beginning for UCO Bank under the agriculture segment through a co-lending arrangement.

About Paisalo Digital Limited:

PAISALO DIGITAL LIMITED (BSE: PAISALO | NSE: PAISALO | BLOOMBERG: PAISALO: IN | ISIN:INE420C01042) is a leading Systemically Important Non-Deposit taking NBFC registered with the Reserve Bank of India.

PAISALO is at the forefront of digital lending, a well-governed, listed Fintech player with a strong distribution network in rural and semi-urban parts of India. The company is a leader in seamless credit distribution, services, and management of small-ticket loans in a Co-Lending tie-up with SBI, BOB, and PNB; with the objective of promoting rural development, self-employment, and women empowerment. PAISALO offers income-generating unsecured loans from INR 10,000 to 3,00,000 through the Individual and Joint lending model provided to entrepreneurs under Priority Sector Lending. The company has served over 1,500,000 borrowers.

About UCO Bank:

Founded on 6th January 1943 by Mr. G.D. Birla, UCO Bank is a commercial bank and Government of India Undertaking. The Bank serves its huge global customer base of over 3074 branches. UCO Bank, with years of dedicated service to the Nation through active financial participation in all segments of the economy- Agriculture, Industry, Trade & Commerce, Service Sector, etc. UCO Bank has marched into the 21st century matched with dynamism and growth.

What Is Accredited Debt Relief, and Is It a Scam?


For many people, hearing the words debt and relief put together makes their Spidey senses tingle. There’s a good reason for this. There are a lot of people out there who want to take advantage of others’ misfortunes. One way to do this is scamming people just looking for a way to get out of debt. Those shopping around for debt relief companies might be wondering, is Accredited Debt Relief a scam?

What Is Accredited Debt Relief, and Is It a Scam?

Anyone who has been there knows the feeling: When you’re deep in debt, any glimmer of hope can seem worth pursuing. The problem is, there are people who make their living looking for individuals just desperate enough to fall into a trap. This is why it’s essential for those shopping around for debt relief to understand some of the warning signs of fraud. These things should be a red flag when looking at debt settlement companies:
  • They ask you to pay fees before setting your debts. While you’ll have to send the debt relief company funds to set aside for negotiations, legitimate organizations won’t charge you for services until debt has been successfully settled.
  • They make you a guarantee. There’s no such thing in the world of debt relief, other than the fact there are no guarantees.
  • They won’t give you information unless you send personal information. This could be a sign of a potential identify theft scheme.
  • It’s difficult to find consumer reviews online. It’s even worse if you find a substantial amount of content warning you against working with the group.
If you don’t already know, Accredited Debt Relief is an organization that specializes in debt settlement. People wondering is Accredited Debt Relief a scam can breathe a sigh of relief, as it’s a totally legitimate business. These are a few features of the company that let you know it’s operating with integrity:
  • They offer free debt consultations for consumers.
  • They are accredited with the American Fair Credit Council (AFCC).
  • They have an abundance of information available to anyone who needs it.
  • They have great reviews from satisfied customers.
All of these elements should help people have some peace of mind in knowing they’re working with a totally legitimate debt relief company. From here, it’s time to think about whether or not Accredited Debt Relief makes sense for you.

What Should Consumers Know about Accredited Debt Relief?

If you need assistance with your debt, working with a debt relief company might be your best bet for finally getting back on track. This is especially true for those who aren’t eligible for debt consolidation or bankruptcy.

The first thing you need to know about Accredited Debt Relief is that they operate through debt settlement. This is also sometimes referred to as debt negotiation. Understanding this is key because debt settlement has a few essential points that can affect you in crucial ways.

With debt settlement, you actually stop paying your lenders directly and instead send money to the debt relief agency. This money you send is then used to negotiate a single payment that’s lower than the amount you owe. The obvious positive here is that successfully settled debts are much less costly than they would be otherwise. But there are also a couple drawbacks you need to know about before signing up for anything.

Since you’re not paying your lenders leading up to the negotiation, it’s likely to negatively affect your credit. This can make it harder to obtain debt in the future; and if you do, it will likely come with unattractive interest terms. Furthermore, settled debts are often considered income for tax purposes. This is something you’ll need to keep in mind when preparing for tax season.

You need to consider the pros and cons of debt settlement before determining wither it’s the right move for you. Fortunately, you can at least know Accredited Debt Relief is not a scam.


Paytm Offering Loan of 2 Lakhs in Just 2-Minutes, Here's The Whole Process


Paytm has started a new facility to give instant personal loans to people a few months back. With this, some special customers of Paytm are given an instant loan up to 2 lakh rupees.

It often happens that you suddenly need money. At this time, if you apply for a loan in the bank, then it takes a lot of time to complete the process. Along with this, many such documents are sought, which you are not able to fulfill. If such a situation comes with you, then Paytm can be a good option for you, because now you can also take a loan from the Paytm with which you were paying the bill.

A few months ago, Paytm has started a new facility to give instant personal loans to people. With this, some special customers of Paytm are given an instant loan of up to 2 lakh rupees, the special thing of which is that you do not have to wait much for this loan. If you are eligible for a loan, then you get a loan of up to two lakh rupees in a few minutes. In such a situation, you know how you can take a loan and what is the whole process of it?

Complete online service

In this Paytm loan, the entire process is done online. You do not have to go to any bank etc. to take a loan.

The special thing is that the entire process of taking a loan is completed in 2 minutes and within two minutes the money is transferred to your account.

You can take advantage of this service of Paytm on National Holiday and Sunday also on holiday, i.e. it can be availed on any day and any time.

Who are eligible ?

This new instant loan is available to job seekers, small business owners and professionals. In this, the loan is given based on your credit score.

Also, this loan of Paytm has to be repaid in 18-36 months and you can pay accordingly. The company has tied up with many NBFCs and banks to provide this facility and you can manage the entire account from the Paytm app.

How to take the loan?

If you also want to take a loan through Paytm, then you will have to complete the further process by going to the Financial Services section of the Paytm app and then clicking on the Personal Loans tab.

After this, you have to give the requested information and your eligibility will be seen and after that money will be transferred to your account.


Market Reports

Market Report & Surveys
IndianWeb2.com © all rights reserved