Showing posts with label Business Tips. Show all posts

From One IoT Deployment to a SaaS Product: How to Scale Without Rebuilding for Every Customer

From One IoT Deployment to a SaaS Product: How to Scale Without Rebuilding for Every Customer

Consider a small software team that has built a cold-chain monitoring system for a logistics operator. Sensors report temperatures from refrigerated warehouses and trucks, while dispatchers receive alerts when conditions put shipments at risk. After months of adjustments, the system runs reliably, the client is satisfied, and five other operators express interest in a similar service.

The team assumes it now has a product to sell. Yet the first prospective customer asks how its contractors will access vehicle data, who will configure new sensors, and whether its own incident procedures can be supported. The requests are reasonable, but answering them means reopening decisions made for the first client. A second deployment is beginning to look almost as labour-intensive as the first.

A successful IoT project is not automatically a SaaS product

An individual IoT deployment is built against a known set of requirements. Devices need to connect reliably, data must reach the right people, and workflows have to match the customer's operations. Meeting those requirements can involve sensible shortcuts: a dedicated integration, manually configured accounts, or rules designed around one team's processes. None of that prevents the project from being a success.

A SaaS product has a different obligation. It must serve organisations that were not involved in its original design without forcing the team to develop, update, and support a separate version for each customer. A founder may see five new contracts as growth; the engineering team may see five separate implementations. The gap between those perspectives can become expensive long before the customer base looks particularly large.

Moving the application to the cloud and charging a subscription will not resolve the problem. Productisation requires deciding which capabilities should be shared, which customer differences can be handled through configuration, and which requests justify individual development. Those decisions shape the roadmap and determine how much additional work comes with every new sale.

For the cold-chain team, the first deployment proves that its software solves a real operational problem. It has yet to establish whether the same value can be delivered repeatedly without turning every customer relationship into another development project.

The second customer exposes the first product decisions

The next logistics operator has a different setup. Some refrigerated vehicles belong to contractors, warehouses use sensors from several manufacturers, and regional managers should only see shipments they are responsible for. Temperature alerts also need to reach different people depending on the cargo, route, and time of day.

The requests themselves are ordinary. The original system, however, may have no way to handle them without code changes. Perhaps device credentials are created manually, access permissions are tied to a fixed organisational structure, or alert rules are embedded in application logic. The first operator never needed anything else, so there was little reason to question those decisions.

The team can accommodate the differences. Engineers add another protocol adapter, adjust permissions, and modify the alerting workflow. But the third customer may bring a different warehouse management system, and the fourth may need separate access for its transport partners. What began as a few reasonable exceptions gradually becomes a collection of customer-specific code, configurations, and deployment procedures.

Those customer-by-customer changes stay with the team after launch. When a bug is fixed or a new feature is released, the team must account for differences between customer environments. Support engineers need to know which configuration or software version each client uses. Even routine changes can require additional testing and coordination.

The warning sign is the amount of engineering involvement required for each new account. If adding a customer means copying an existing deployment and then modifying it until it fits, the company is still largely delivering projects. To change that pattern, the team needs to identify which parts of the system should become reusable product capabilities before those differences multiply.

What should become reusable before the next customer arrives

The first priority is to separate functions that every customer needs from the features that make the product valuable in its particular market. For a cold-chain monitoring service, the differentiating features might include shipment tracking, temperature compliance rules, exception reporting, and integrations with logistics systems. But creating customer accounts, connecting devices, assigning permissions, and maintaining equipment are recurring requirements regardless of the operator.

These common functions should work through established processes rather than being recreated for each deployment. A new customer organisation needs its own users, devices, data, and access boundaries. Equipment should follow a consistent provisioning process, with credentials and ownership recorded from the start. Firmware updates, configuration changes, and troubleshooting also need to work across customer fleets without requiring separate maintenance procedures.

A reusable foundation for multi-tenant device management helps bring these operations into a common model. Customer onboarding, tenant isolation, and device lifecycle management can be handled through established platform capabilities instead of custom implementation work. This is particularly useful when clients have different organisational hierarchies or involve external partners who need restricted access to certain equipment.

Building every one of these capabilities specifically for a new SaaS product is possible, but it also means taking responsibility for developing and maintaining functions that are largely independent of the product's competitive advantage. Starting with prebuilt IoT modules allows a team to concentrate more of its engineering effort on the workflows, integrations, and customer experience that distinguish its service.

Reusability does not mean that every customer must share the same physical infrastructure. Some organisations may need dedicated environments because of security policies, contractual requirements, or operational constraints. What matters is whether those environments can be provisioned, configured, monitored, and updated through a repeatable delivery model.

Keep the product configurable without turning it into custom software

One logistics operator may need alerts based on strict temperature thresholds, while another uses different rules for pharmaceuticals, frozen food, and fresh produce. Their reporting requirements and escalation procedures may differ just as much as their equipment.

Many of these differences belong in configuration rather than application code. Temperature limits, notification recipients, user permissions, and reporting schedules can be defined per customer while the underlying mechanisms remain unchanged. The product supports different operating practices without maintaining a separate implementation for each one.

Other requests call for extensions. If a customer needs to exchange shipment data with a particular transport management system, the team might develop an integration adapter that becomes available to other customers. A new reporting capability could follow the same approach. The initial request comes from one organisation, but the resulting functionality becomes part of a product that serves many.

Some requirements will still justify bespoke development. The important question is whether a requested change belongs in the shared product, can be isolated as an extension, or should remain outside the standard offering. That decision involves more than technical feasibility. The team must consider likely demand, maintenance costs, and the effect on its roadmap.

Configuration itself also needs limits. An application with hundreds of interdependent settings can become nearly as difficult to maintain as multiple custom deployments. The aim is to support meaningful customer differences through a manageable set of options, rather than make every aspect of the software independently adjustable.

Make onboarding, billing and support part of the product model

Reusable software solves only part of the delivery problem. The team also needs a consistent path from a signed contract to a working service.

For the cold-chain platform, that process might involve creating a customer account, assigning administrators, registering equipment, selecting alert templates, and connecting any required external systems. Some steps may still require assistance, particularly where physical devices are involved. A useful test is whether an implementation specialist can onboard the next operator using a documented procedure without developers modifying the application or relying on undocumented workarounds.

AWS makes this distinction explicit in its SaaS design principles, recommending a single, repeatable tenant onboarding process and tenant-aware operations. The same guidance recognises that customers may have different isolation requirements and service expectations without needing entirely separate product versions.

Billing introduces its own operational questions. Subscription plans, service tiers, usage limits, and feature entitlements need to correspond to capabilities the product can actually deliver. If a customer upgrades to more advanced reporting or adds another operating region, the change should ideally be handled through established account and configuration procedures rather than a new development request.

After launch, support engineers need to identify which tenant owns an affected device, inspect its configuration, review relevant events, and distinguish customer-specific problems from platform-wide incidents. Updates should also follow a controlled release process, with enough consistency across deployments to avoid maintaining several incompatible versions.

Each extra onboarding step, support exception, or customer-specific release adds to the cost of serving that customer. Revenue may increase with each new subscription, but profitability depends partly on how much onboarding, support, and maintenance effort accompanies that growth. A product that can accommodate additional customers without continuously expanding its implementation workload has a much stronger basis for sustainable growth.

Product ownership matters more as the customer base grows

As the cold-chain platform attracts more operators, decisions that once seemed purely technical begin to affect what the company can sell. A larger customer may require a dedicated hosting environment. Another may need integration with its fleet management software or support for equipment that the original platform never anticipated. The team needs enough control over its technology to respond without having

How Can a Business Car Lease Support Companies During Expansion?

How Can a Business Car Lease Support Companies During Expansion?

As companies expand, managing a larger fleet can mean more servicing, unexpected repairs and vehicle downtime. Buying additional vehicles also ties up capital in assets that depreciate over time. A car lease can help companies meet growing mobility needs while reducing the burden of fleet ownership.

A business car lease solution can support expansion by helping you add vehicles as you enter new locations, hire more employees, or strengthen customer support.

This blog explains how strategic fleet management can support business expansion, improve operational efficiency, and help you manage your growing vehicle requirements.

What Changes When a Business Starts Expanding?

Growth reshapes how a company manages capital and daily operations. Expanding into new territories or expanding sales teams requires physical mobility, but buying vehicles outright ties up vital financial resources.

Purchasing a commercial fleet locks liquidity into depreciating assets. Expansion demands agility, meaning companies need predictable overheads rather than sudden capital expenditures. Furthermore, managing vehicle maintenance, registration, and insurance internally distracts leadership from core revenue generation.

To keep growing without putting pressure on their finances, organizations are turning to corporate mobility solutions. Modern leasing models help enterprises maintain financial flexibility while keeping workforce mobility seamless.

Where Can a Car Lease Fit into Business Expansion Plans?

Integrating a business car lease into strategic scaling offers immediate operational flexibility and capital efficiency.
  • Team Onboarding and Deployment: Provide transport support for new employees who need to travel for work. It serves as an attractive recruitment perk that simplifies daily field logistics for new hires.
  • Flexible Fleet Size: Add or reduce vehicles based on your business needs. This gives you the flexibility to handle seasonal demand and short-term projects without taking on long-term vehicle ownership.
  • Liquidity Optimization: Avoid tying up a large amount of capital in vehicle purchases during an expansion phase.
By relying on structured corporate mobility solutions, companies scale their vehicle usage up or down according to actual operational demand.

How Can Vehicle Requirements Differ Across Growing Teams?

A single vehicle profile rarely suits an entire enterprise. Structuring a flexible car lease framework allows organizations to tailor automotive arrangements to distinct internal needs:
  • Executive Compensation and Perks: Providing company vehicles serves as a powerful retention tool. A structured business car lease can form part of a tax-efficient CTC restructuring or serve as an executive reward. Vehicle tiers scale naturally from mid-level managers up to C-suite leadership.
  • Specialized Logistics: Certain functions call for customized Light Commercial Vehicles (LCVs) or transport fleets. Choosing vehicle leasing for operational units ensures functional requirements, like cargo configurations or custom branding, are met under fixed monthly rates.

What Should Businesses Review as Their Fleet Requirements Increase?

As a commercial fleet expands, maintaining oversight becomes increasingly complex. Businesses evaluating a business car lease partner should assess key parameters:
  • Maintenance and Support Protocols: Ensure all service work is performed exclusively at Original Equipment Manufacturer (OEM)-authorized service centers. Round-the-clock roadside assistance and temporary replacement vehicles keep employee downtime to a minimum.
  • Risk and Depreciation Management: Pick a car lease program that shields your organization from market depreciation risks, total loss exposure, and unexpected repair surcharges.
  • Fleet Tracking and Compliance: Real-time vehicle tracking systems, usage analytics, and automated traffic fine reporting provide necessary oversight as the fleet grows across regions.
  • Nationwide Coverage: Select a partner offering unified support across all operating locations. Standardized service networks ensure consistent driver safety and maintenance access.
Leveraging modern corporate mobility solutions equips companies with transparent dashboards, structured policies, and streamlined operations across every branch.

Accelerate Your Growth with a Smarter Fleet Strategy

Expanding your company should never be slowed down by vehicle problems or confusing paperwork. Choosing a complete business car lease strategy gives your organization full financing, predictable monthly costs, and total freedom.

By handing over maintenance, registration, insurance, and administrative work to corporate vehicle leasing partners like Avis Lease, business owners can focus completely on reaching their primary business goals. Modern leasing plans protect your money while keeping growing teams on the move. Ultimately, smart vehicle management acts as a strong boost for long-term growth, simple operations, and lasting business success.

How a Sustainability Business Model Can Unlock Long-term Profits

How a Sustainability Business Model Can Unlock Long-term Profits

As businesses face increasing environmental challenges and shifting consumer expectations, sustainability business models are becoming a key factor in long-term success. Companies are realizing that sustainability isn't just about doing good for the planet; it can also unlock new opportunities for growth and increase profitability.

By focusing on energy efficiency, businesses can position themselves for long-term financial success. In this blog, we will read how adopting a sustainability business model can benefit companies and help them achieve lasting profitability.

What is a Sustainability Business Model?

A sustainability business model integrates environmental, social, and economic considerations into a company’s operations. It goes beyond just using green energy or recycling; it’s about creating a business strategy that benefits both the company and the world in the long run.

This model could include using renewable energy, reducing waste, and sourcing materials responsibly. By focusing on these factors, businesses can grow while also having a positive impact on the environment and society.

Why Sustainable Business Models Make Financial Sense

Embracing a sustainability business model is not just about environmental responsibility; it’s about making smarter decisions that support long-term profitability. Here’s why it makes financial sense:

Cost Savings: Implementing energy-efficient technologies, optimizing resource use, and reducing waste all contribute to lowering operational costs. These savings, once realized, can be reinvested into the business for further growth.

Regulatory Compliance: Governments are tightening environmental regulations, and businesses that adopt sustainability practices early are well-positioned to avoid penalties, comply with regulations, and remain competitive in a shifting landscape.

Stronger Brand Reputation: Consumers are usually drawn to brands that show they care about the planet. By prioritizing sustainability, businesses not only improve their reputation but also attract customers who value ethical and sustainable practices.

Attracting Investment: Investors are placing more value on businesses that show a commitment to sustainability. A sustainability business model makes companies more appealing to investors looking for long-term, responsible growth opportunities.

The Long-term Benefits of Sustainability

Adopting a sustainability business model isn’t just a short-term fix; it has long-term financial benefits:

Resilience: Sustainable businesses are more prepared for future challenges like resource shortages or price fluctuations in energy markets. They are more adaptable to the changes in global supply chains and regulations.

Innovation: Sustainability often drives innovation. Companies that focus on improving their environmental impact are more likely to find new ways to improve operations, develop new products, and create efficiencies that give them an edge over competitors.

Employee Engagement: Employees are also looking to work for companies that align with their values. A company that embraces sustainability is more likely to retain top talent, leading to improved productivity and a positive workplace culture.

How to Transition to a Sustainability Business Model

For businesses looking to adopt a sustainability business model, the transition can be done in several steps:

Assess Your Impact: Start by understanding your current environmental impact. Identify where you use the most energy, produce the most waste, or consume the most resources, and look for ways to reduce that footprint.

Engage Your Team: Sustainability requires buy-in from all employees. Encourage staff to contribute ideas, adopt sustainable practices in their work, and help foster a culture of sustainability across the organization.

Communicate Your Efforts: Transparency is key. Make sure your customers, investors, and other stakeholders know about the sustainability practices you are implementing. This helps in building trust and shows that you are serious about your commitment.

Partner with Experts: Collaborating with other businesses or experts who specialize in sustainability can help you implement the best solutions tailored to your needs. They can provide guidance, technology, and best practices to ensure your sustainability efforts are successful.

Unlocking Profitability with Sustainability

A sustainability business model is not just about being eco-friendly; it’s a smart strategy for ensuring long-term profitability. By reducing operational costs, improving efficiency, and building a strong brand reputation, companies can reap the financial rewards of sustainable practices. Furthermore, businesses that lead in sustainability create value for all stakeholders, from consumers to investors to employees.

To make this transition successful, it’s important to partner with trusted experts and sustainable technology providers. This partnership will help you implement effective solutions, stay up-to-date with industry trends, and ensure that your business is contributing to a sustainable and profitable future.

What Every SME Should Know About GST Number Search

What Every SME Should Know About GST Number Search

Understanding GST number search is central to the way small and medium enterprises operate today. The importance of verifying a GST number extends far beyond simple compliance, as it helps protect your SME from potential fraud, loss of input tax credit and audit issues.

A GST number or GSTIN functions as a unique identifier for businesses registered under India’s Goods and Services Tax regime. It plays a key role in ensuring trustworthy transactions and transparent tax practices for every business owner and partner.

Many SMEs face challenges when managing suppliers or onboarding new customers. Without a solid GST number search process, you risk dealing with unregistered or non-compliant entities. That can lead to avoidable legal complications, delayed input credits and operational hurdles.

This blog explains everything you need to know about GST number search. You will learn what it is, how to perform it and why it matters for every SME aiming for sustainable growth and reliability in Indian business.

What is a GST number and why does it matter?

A GST number is a 15-digit code assigned to businesses registered under GST in India. It’s built from your PAN, a state code, entity number and a unique check digit. For SMEs, knowing and verifying GST numbers is part of building resilient relationships with vendors, clients and statutory bodies.

Citing the correct GST number ensures you get input tax credit and lowers your risk during audits. The GSTIN must be included on all invoices, e-way bills and tax returns. Missing or incorrect GST numbers can result in compliance issues and potential financial penalties.

How SMEs can conduct a GST number search

Knowing the correct process helps you avoid costly errors, prevent fraudulent dealings and build stronger relationships with your suppliers or clients. SMEs can use both official government sites and trusted third-party platforms to conduct these searches efficiently.

1. Official GST portal

Visit the official GST website and click ‘Search Taxpayer’. Enter the GSTIN, PAN or business name. This shows registration status, addresses and more official details.

2. Search by GSTIN

Enter the 15-digit GST number to instantly view business details, registration status and filing compliance.

3. Search by PAN

If you only have a PAN, use the portal’s option to list all GSTINs linked with that PAN. This is handy when suppliers have multiple registrations.

4. Company name search

Some secure third-party tools let you search using a trade or legal name. After locating a GSTIN, always cross-check it using the GST portal or another reliable site for absolute certainty.

What SMEs gain from GST number verification

GST number search adds a critical layer of security. For entrepreneurs and SME managers, the biggest benefits include:
  • Staying away from suppliers using fake or deregistered GST numbers
  • Safeguarding input tax credit claims by using only genuine GSTINs
  • Getting all business invoices and statutory records in perfect order
  • Protecting your business during government audits and tax assessments
  • Ignoring GST verification exposes your SME to fraud, compliance slips and unnecessary financial losses.

4 tips to perfect your GST number search

Mastering GST number search goes beyond simply locating a GSTIN; it is about refining your verification process to safeguard your SME from potential errors or compliance issues.

Here are practical tips that every business owner should integrate into their regular workflow for reliable and secure GST operations.
  1. Always use the official GST portal or reputable third-party sites when checking GST numbers.
  2. Verify the registration status, business name and address linked to each GSTIN.
  3. Double-check the GST number structure: valid GST numbers follow a specific pattern with identifiable state and PAN details.
  4. Keep a record of every GST verification for future reference and audits.
Careful checks now can save hours of trouble later. Together, these steps can make your verification process more reliable and audit-ready.

Secure your SME: Take action with a reliable GST number search

Staying proactive with GST number search can define your SME’s long-term success in India’s competitive market. Every verification you carry out helps prevent costly errors and ensures your tax input credits are legitimate and traceable. With GST compliance integral to audits and partnerships, your efforts today create lasting trust and credibility for your business.

Ready to take control of your SME’s compliance and credibility? Start your GST number search today with a trusted tool from Pine Labs. Validate every new partner, and ensure every transaction meets the highest standard of trust. Learn more at https://www.pinelabs.com.

Smart Tips on How to Get Digital Marketing Right

Smart Tips on How to Get Digital Marketing Right

It is amazing just how many businesses around the world still haven’t grasped the importance of getting their digital marketing strategy right. In the modern world where everything seems to be in demand in an instant, having a robust digital marketing plan leads to increased sales by those on the go and increasingly using their mobile devices to make purchases.

It is understandable that some do get it wrong, as they do not have the resources to employ a dedicated team. Those in that position are advised to outsource the work to a digital marketing agency that provides guarantees as found by contacting King Kong. Those who decide to give it a go in-house can follow some of the following smart tips to get their marketing right.
  • Making the most of data that can be found by those with the requisite skills and experience allows for money to be spent more effectively while scalability is provided. The data can provide details of demographics and habits which can be utilised to target the right audience and is especially important when implementing SEO.
  • Setting a budget and following it closely is important, especially in the initial stages of any strategy being implemented. An error many make is not having a concerted plan and throwing money at a project without receiving any tangible results. This can quickly get out of control and leave a financial hole elsewhere.
  • Providing the best user experience for those who visit a website offers a far greater opportunity for them to be converted into cash-purchasing customers and build brand loyalty. If they find a site that is uninformative and not easy to navigate, they are unlikely to return, no matter its ranking on the Google listings.
  • Building an affinity between customers and a business will ensure that they continually return if they enjoy their experience. Credibility built through adding backlinks on a website to authoritative bodies can help in this department while sometimes building partnerships elsewhere.
  • Exploring the opportunities provided by social media will also increase visibility if implemented properly through smart posts which are ads. Before they know it, an interesting piece redirects those viewing to a landing page where they may be tempted to buy items and continue to return.
Getting a digital marketing strategy right can make the difference between success and failure for any business, that should outsource the services if they are short of resources.

The Benefits of Implementing Knowledge Management in Organizations

The contemporary business environment is teeming with information, to the extent that managing this vast trove of knowledge can be a daunting task. Recognizing the critical role that information plays in success, forward-thinking organizations are diligently adopting knowledge management strategies. Knowledge management is not just about storing information; it's about unlocking the full potential of an organization's intellectual assets. By systematizing and sharing expertise, companies can streamline processes, foster innovation, and maintain a competitive edge. Below, we explore the multifaceted benefits that knowledge management affords to organizations.

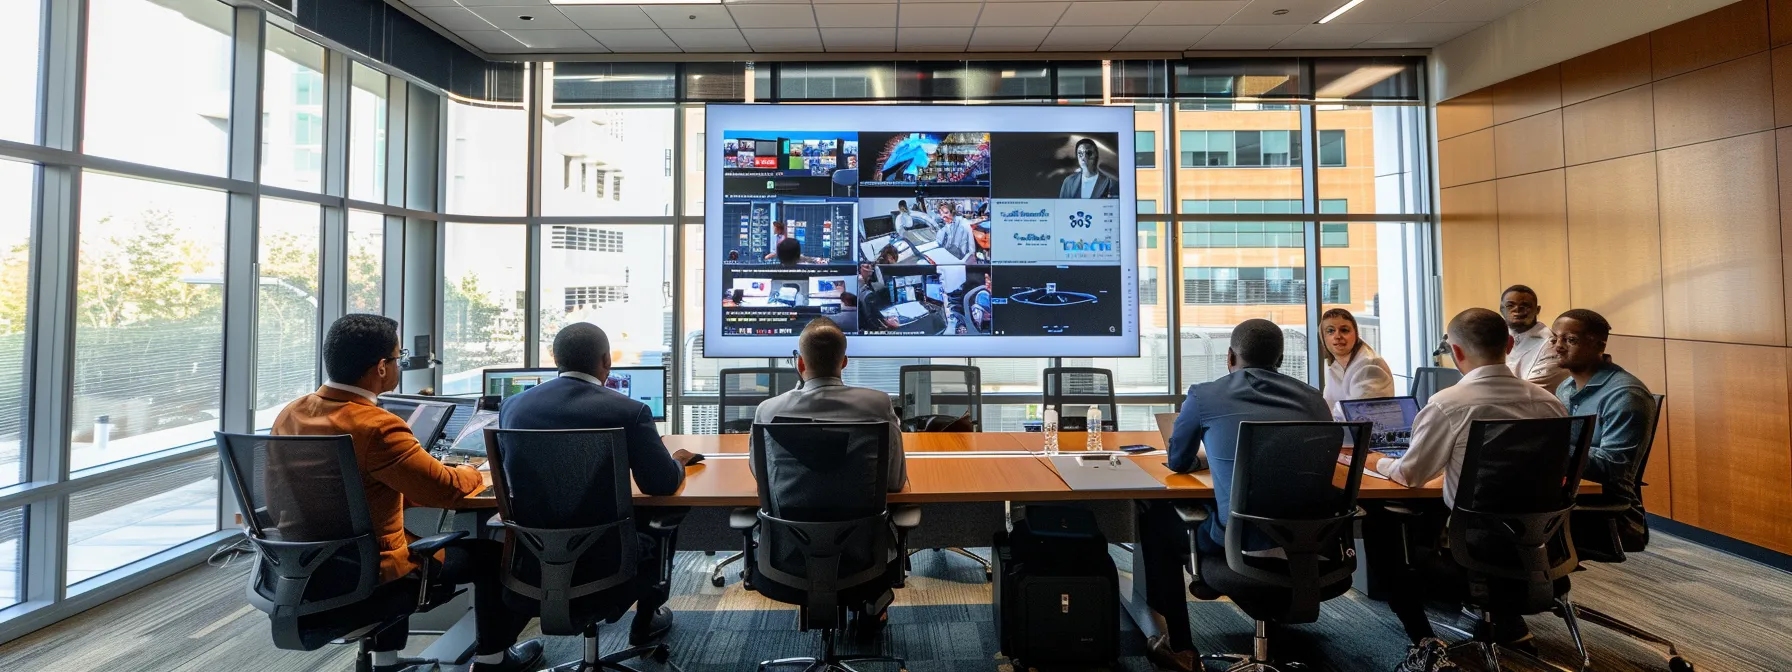
Attendees in a conference room focused on a video discussing effective knowledge management practices.

Unlocking Organizational Wisdom: The Power of Knowledge Management

The rise of knowledge economies has highlighted the importance of intellectual capital, with knowledge management playing a crucial role in capturing and sharing this asset. By creating knowledge repositories, companies empower employees to access valuable information like best practices and historical data, which enhances decision-making and saves time by preventing redundant efforts. This also preserves institutional memory, ensuring smooth operations even during staff changes.

Knowledge management also fuels innovation by allowing employees to tap into diverse insights and combine them in new ways. Centralizing customer feedback and preferences enables businesses to deliver personalized and efficient service, improving overall customer satisfaction.

Fostering Innovation and Collaboration Through Knowledge Sharing

Knowledge sharing is a vital aspect of innovation and collaboration in any organization. It allows for the free flow of information, unlocking creative potential and fostering new ways of thinking. Collaborative technologies like intranets and social media tools have revolutionized employee interaction, enabling teams to tackle complex problems collectively. This connectivity accelerates project timelines and builds a unified corporate culture that values knowledge sharing.

Routine sharing of insights among departments breaks down silos, fostering a more cohesive business strategy and surfacing unique solutions. A strong knowledge-sharing ethos also fosters a sense of community and belonging, attracting top talent and retaining them in a workplace where innovation and collaboration are ingrained values.

Enhancing Decision Making with Streamlined Information Access

Knowledge management systems are essential for effective decision-making by organizing data in a comprehensible and retrievable manner. They eliminate the need for cumbersome searches and inconsistency, allowing decision-makers to act swiftly and confidently. These systems benefit all organizational levels, from executives to frontline staff, enabling them to make informed choices that align with company goals.

Analytics are often integrated into knowledge management technology to help identify patterns and trends from vast data sets, guiding future decisions and allowing organizations to adapt to market or customer behavior changes. Streamlined access also allows for more accurate identification and assessment of potential opportunities and risks, enabling companies to mitigate risks before they escalate and capitalize on emerging opportunities before they are seized by competitors.

Cultivating a Learning Organization for Continuous Improvement

A team of professionals seated at a table, reviewing documents and sharing ideas during a meeting.

Knowledge management principles are essential for creating a learning organization that prioritizes continuous improvement. This involves capturing, analyzing, and disseminating knowledge from daily operations. Learning organizations invest in training and development to ensure their workforce is skilled in using knowledge tools and contributing to the knowledge base.

They view failures as valuable learning opportunities and document lessons, fostering a culture of resilience and adaptability. This approach not only improves processes but also enhances employee engagement, as they are more likely to take ownership of their work and contributions.

Leveraging Knowledge Management for Competitive Advantage

Knowledge management is crucial for companies to adapt and innovate in a rapidly changing business landscape. It allows organizations to leverage collective expertise and navigate market complexities with agility, providing a competitive advantage for long-term success. Effective knowledge management also helps companies identify and respond to customer needs, securing customer loyalty and attracting new customer segments.

Strategic partnerships and alliances are also beneficial, as they contribute to growth and expansion. A robust knowledge management framework also aids in risk management, allowing companies to implement preemptive measures and strategies, conserving resources and reinforcing their reputation as resilient operators.

Overall, the integration of knowledge management into organizational practices offers a wealth of benefits. It catalyzes innovation, sharpens decision-making, and forges a culture of continuous learning and improvement. By treating knowledge as a strategic asset, companies foster a dynamic environment that drives both internal growth and competitive advantage. Knowledge management may just be the keystone of modern business success.

Top Tech for Business Leaders: From Search as a Service to Network Monitoring Software

The contemporary business landscape is an ever-evolving space where technology plays a central role in shaping operations, efficiency, and competitive edge. Business leaders are continuously looking for robust tech solutions to stay ahead of the curve, from enhancing their digital presence to securing their network infrastructure. These technological advances provide a significant opportunity to optimize business processes, make data-driven decisions, and ensure the security and reliability of digital assets. This article will explore the most impactful technologies that savvy business leaders should consider incorporating. Keep reading to discover how tech-like search as a service and network monitoring software can elevate your business strategy.

Exploring the Advancements of Search as a Service for Business

img

As the volume of digital content grows exponentially, businesses face the challenge of effectively managing and retrieving information. Search as a service offers a powerful solution by providing sophisticated, cloud-based search capabilities that can be integrated into various platforms. The ability to rapidly access relevant data can increase productivity and improve customer experience.

Search as a service platform utilizes advanced indexing and search algorithms to deliver accurate and timely results. This technology can be finely tuned to meet specific business needs, ensuring that employees and customers find precisely what they want. With data spread across numerous sources, this centralized search function becomes an indispensable tool for any organization.

User experience is at the heart of search as a service. It enables businesses to offer intuitive and responsive search interfaces that cater to the expectations of modern users. Moreover, this technology can be scaled to accommodate growing amounts of data, guaranteeing that search performance remains efficient regardless of a business's digital footprint.

The agility offered by search as a service means businesses can rapidly adapt to changing circumstances, such as adding new data sources or altering search criteria. This responsiveness can provide a significant competitive advantage in today’s fast-paced market.

Network Monitoring Software: Ensuring Business Continuity and Security

Two professionals discuss the benefits of utilizing network monitoring software to ensure business continuity and security.


Network performance and security are paramount for maintaining business continuity in today's interconnected world. Effective network monitoring software is essential for enabling organizations to oversee their network infrastructure and ensure smooth and secure operation.

Such software provides real-time visibility into network activities, allowing IT teams to detect and address issues promptly. This proactive approach minimizes downtime, which can have a costly impact on operations and reputation. Network monitoring tools can be invaluable in preempting disruptions and keeping business services available to customers and employees alike.

Beyond maintaining operational stability, network monitoring plays a vital role in security. It helps identify unusual network behavior that may indicate a security breach, enabling rapid response to potential threats. In an era where cyberattacks are increasing in frequency and sophistication, robust network monitoring is a crucial component of a comprehensive security strategy.

Additionally, network monitoring facilitates capacity planning, helping businesses forecast their infrastructure needs. This foresight allows for strategic investment in network expansion, ensuring it aligns with growth objectives and doesn’t become a bottleneck for progress.

Investing in Scalable Tech Solutions for Long-Term Business Growth

Investing in scalable tech solutions is a strategic imperative for businesses looking toward the future. Technologies that can grow in tandem with a business are essential, as they provide a foundation that can support expansion without the need for continuous, costly overhauls.

Scalability is not solely about handling increased volume; it's also about the capacity to integrate new features, services, and capabilities. As businesses evolve, the tech they depend on must be adaptable, incorporating innovations to deliver a sustained competitive edge.

Another aspect to consider is user adoption and training. Investing in intuitive and widely adopted technologies can reduce the learning curve and enhance productivity. Business leaders should consider the human element of technology deployment to maximize return on investment.

Lastly, businesses must not overlook the importance of strategic partnerships in pursuing growth. Aligning with tech providers that understand a business's unique needs can lead to customized solutions that drive success. These partnerships allow companies to leverage specialized expertise, keeping them well-equipped for future challenges.

Altogether, embracing cutting-edge technologies empowers business leaders to enhance efficiency, bolster security, and adapt swiftly to evolving market dynamics. By investing in scalable tech solutions, businesses lay the groundwork for sustained growth and innovation, ensuring they remain competitive in a rapidly evolving landscape. Strategic partnerships with knowledgeable tech providers further fortify organizations, equipping them with tailored solutions to navigate complex challenges and seize opportunities for success.

Interpreting News and Economic Data in Forex: A Guide for Traders

Interpreting News and Economic Data in Forex: A Guide for Traders

For forex traders, the constant flow of news and economic data releases can seem like an endless barrage of noise. However, those who learn to interpret this data effectively can uncover a potential goldmine of trading opportunities. Understanding how to analyze news and economic reports is crucial for anticipating market movements and making informed trading decisions.

Fundamentals Trump Everything

At its core, the forex market is driven by economic fundamentals. Central bank policies, interest rate differentials, GDP growth, inflation, employment data — these are the forces that ultimately shape currency valuations over the long run. While technical analysis has its place, forex is a fundamentals game first and foremost. That’s why the leading trading platforms like the mt4 download for pc offer various features for fundamental analysis, such as economic calendars and news feeds.

When a major economic report like the Non-Farm Payrolls or Consumer Price Index gets released, currency markets can experience drastic volatility as traders position themselves based on the implications of the new data. A strong jobs report, for example, increases the odds of future rate hikes by the Federal Reserve, boosting the US dollar's appeal. Conversely, soft inflation numbers may convince traders that the Fed will pause its tightening cycle, weakening the greenback.

Trader's Tactics: A Step-by-Step Guide, 

1. Mark Your Calendars

Having a forex economic calendar that highlights all relevant data releases is essential. Financial news platforms typically provide comprehensive calendars, as do most brokers and trading platforms. Get into the habit of consistently reviewing upcoming events.

2. Study the Consensus Forecasts

Most data releases are preceded by economist predictions of what the actual numbers will be. Referred to as the consensus forecast, this is the yardstick against which the market judges whether the release was stronger or weaker than expected. Smart traders examine consensus forecasts ahead of time.

3. Prepare for Volatility

Regardless of how the numbers print relative to forecasts, data releases inject tremendous volatility into the markets — this is when the biggest intraday price moves tend to occur. Reduce position sizes or avoid taking positions altogether in the hours before a high-impact release.

4. Filter the Noise

Not all releases are created equal. Non-farm payrolls, inflation reports, GDP figures, and FOMC rate decisions are among the most impactful for the US dollar. Other releases like consumer confidence or existing home sales, while still relevant, tend to have more muted impacts. Identify the highest-priority reports to focus your analysis efforts on.

5. Look for Revisions

Data releases often contain revisions to previous figures in addition to the latest numbers. These revisions can sometimes overwhelm the impacts of the new data itself. Traders should account for both when analyzing the overall implications.

6. Monitor Accredited Sources

In the internet era, unfounded rumors can spark bouts of irrational volatility. Monitor newswires like Reuters and Bloomberg as well as official statistics agencies for your traded currencies' economies. Avoid taking positions based on unsubstantiated chatter on forums or social media.

Interpreting News and Economic Data in Forex: A Guide for Traders

Mastering the News Reaction

Correctly interpreting how traders are likely to react to incoming news is an art form. Sometimes, the market's intuitive reaction may seem contradictory. For example, a strong employment report that should theoretically boost the currency might instead spark US dollar selling if traders view it as increasing the odds of an economic overcooking and excessively tight monetary policy.

The key is developing an intuition for how markets “think” by studying past reactions to similar data. This perspective enables formulating views not just on what the numbers themselves represent, but on how traders are prone to reposition themselves based on the implications.

News Trading Versus Fundamental Analysis

It's important to distinguish the practice of explicitly trading newsworthy events from conducting fundamental analysis more broadly. Executing trades specifically around scheduled news releases is an inherently short-term tactic focused on capitalizing on volatility around those events.

By contrast, fundamental analysis in forex involves assessing the overall state of an economy by weighing factors like GDP growth, inflation trends, trade dynamics, productivity figures, monetary policy outlook, and market sentiment. While high-impact news releases certainly influence fundamental traders' perspectives, their strategies tend to play out over longer timeframes.

The Pursuit of an Edge

At the end of the day, successfully navigating the forex markets requires traders to relentlessly pursue and protect any analytical edge they can muster. By developing robust skills in interpreting news and economic data, traders can put themselves in a position to consistently identify high-probability trading opportunities before others. Combined with disciplined risk management, this skill set can prove invaluable in the perpetual quest for profitability.

Tips for Maximizing the Benefits of Enterprise Reporting

The ways that businesses collect analyze,e and use data have greatly changed over the years. With the vast growth of technology, enterprise reporting is increasingly becoming a significant factor in the success of any business. Accurate and timely enterprise reporting can lead to more informed decisions, improved operational efficiency, better customer relations, and increased profits. Keep reading to learn how to leverage enterprise reporting to meet your business goals.

Understanding the Importance of Enterprise Reporting

A team in an office discussing enterprise reporting during a meeting


The advent of modern technology and digital prowess has transformed how businesses operate, making enterprise reporting play a pivotal role. It entails gathering and analyzing data to help make crucial business decisions. By applying enterprise reporting, businesses can track their performances regularly, making it easier to spot trends, problems, and opportunities.

Enterprise reporting offers an encompassing view of business operations. This, in turn, enables leaders to make data-driven decisions that can improve their bottom lines. Effective enterprise reporting strategies also promote transparency, helping stakeholders to easily understand the overall state of business within a given period.

Lastly, enterprise reporting can dramatically streamline workflow. It eliminates data redundancy and tedious manual processes, creating a more efficient operational system. This benefit, in turn, leads to increased productivity and cost savings.

Mastering the Art of Data Collection for Business Intelligence

Enterprise reporting thrives on accurate and timely data, which makes mastering data collection techniques crucial. The process begins with identifying relevant data sources. The sources could be internal, such as business process data, or external, like market trends and customer demographics.

Businesses should also automate their data collection processes whenever possible. Automation eliminates errors and inconsistencies associated with manual handling, thus ensuring the quality of the collected data. In situations where large amounts of data are involved, businesses can leverage data collection technologies. These technologies not only simplify the collection process but also facilitate the real-time updating of data, making it easier for organizations to make quick, data-driven decisions.

Lastly, businesses should designate data handling teams to ensure all data is handled efficiently. These teams will oversee the collection, curation, analysis, and report generation processes; thereby enhancing the integrity of your enterprise reporting.

Leveraging Reporting Tools for Detailed Enterprise Analysis

A man in an office studying enterprise reporting

Advancements in technology have brought forth a plethora of reporting tools that businesses can use for in-depth analysis. These tools vary in functionality, so it's essential to choose the ones that best fit your business needs. A good tool should simplify data analysis, making it easy to extract actionable insights.

Apart from simplifying analysis, these tools can also automate the reporting process. This automation reduces the time taken to generate reports, thereby allowing more time to strategize based on the insights provided. Furthermore, automated reports will be consistent, accurate, and timely; ensuring your business stays ahead of its operational and market trends.

It's important to ensure that the selected tools are user-friendly and align with your business workflow. A tool that requires minimal technical expertise to operate will foster wider adoption across the organization, thereby optimizing the benefits got from your enterprise reporting.

Enhancing Decision-Making With Advanced Enterprise Reporting

Using advanced enterprise reporting bolsters the decision-making process in your business. With detailed enterprise reports availed in real-time, decision-makers can formulate strategies that reflect the current business environment.

Reports can unveil customer behaviors and preferences, empowering businesses to fine-tune their products and services to meet customer needs better. This enhancement will, in turn, lead to increased customer satisfaction and loyalty, boosting your business's competitive advantage.

Ultimately, advanced enterprise reporting aids in setting realistic goals. By understanding where your business currently stands, you can set achievable objectives that will guide your company to continued success.

Overall, the significance of an effective enterprise reporting system in decision-making and goal achievement cannot be overstated. Leveraging this tool can significantly contribute to your business' growth and success.


Understanding the Smart Payout Strategies and Crafting Compelling Payment Pages!

Understanding the Smart Payout Strategies and Crafting Compelling Payment Pages!

In today's digital age, where businesses thrive on the online landscape, understanding smart payout strategies and crafting compelling payment pages has become a paramount concern. In this article, we will explore the complexities surrounding these two pivotal elements that wield substantial influence on the prosperity of your digital endeavour.

Smart Payout Strategies: Maximising Efficiency and Customer Satisfaction

Different Smart Payout Approaches

Smart payouts are not one-size-fits-all. There are various approaches that businesses can adopt to disburse funds efficiently. These include:

Instant Payment Transfers

In the era of instant gratification, customers appreciate quick payouts. Employing instant payment transfers ensures that your customers receive their funds promptly, enhancing their satisfaction with your service.

Scheduled Payouts

For businesses with recurring payment needs, scheduling payouts at regular intervals streamlines the process. This method minimises manual intervention and reduces the risk of errors.

Flexible Payment Options

Offering multiple payout options, such as bank transfers, digital wallets, or even cryptocurrency, caters to a diverse clientele. Providing flexibility in payment methods can give your business a competitive edge.

Benefits of Smart Payouts

Implementing smart payout strategies offers several benefits:

1. Improved Customer Retention

Efficient payouts lead to happier customers. Satisfied customers are likelier to stay loyal to your brand and recommend it to others.

2. Cost Savings

Automated payout processes reduce operational costs associated with manual handling. This frees up resources that can be invested elsewhere in your business.

3. Enhanced Security

Smart payout systems often have robust security measures to protect sensitive financial data. This instils trust in your customers, which is crucial for online transactions.

Payment Page Design: Creating a Seamless User Experience

About Payment Page Experience

The payment page represents the last interaction in the customer's path, and it's crucial to ensure its seamless operation. Points to take into account encompass:

User-Friendly Interface

A clutter-free and intuitive design ensures customers can easily navigate the payment page. This reduces the likelihood of cart abandonment.

Mobile Optimisation

Given the rise in mobile transactions, your payment page must be responsive and mobile-friendly. This ensures that customers can complete payments from any device seamlessly.

Clear Call-to-Action

The payment button should be prominent and labelled clearly, leaving no room for ambiguity. Customers should know precisely how to proceed.

Security Measures

Customers need assurance that their payment information is secure. Incorporating robust security measures on your payment page is imperative. These measures may include:

1. SSL Encryption

Using Secure Socket Layer (SSL) encryption ensures that data transmitted between the user's browser and your server remains confidential and protected.

2. PCI DSS Compliance

Adhering to Payment Card Industry Data Security Standard (PCI DSS) requirements ensures that credit card data is handled securely, reducing the risk of data breaches.

3. Two-Factor Authentication

Implementing two-factor authentication adds an extra layer of security, safeguarding against unauthorised access.

Crafting a Compelling Payment Page: Best Practices

1. A/B Testing

Continuously monitor and improve your payment page by conducting A/B tests. Analysing customer behaviour can help you identify areas for enhancement.

2. Customer Feedback

Listen to your customers. Their feedback can provide valuable insights into pain points in your payment process.

3. Streamlined Checkout Process

Minimise the steps required for checkout. The simpler and faster the process, the more likely customers will complete their transactions.

Conclusion

In conclusion, understanding smart payout strategies and crafting compelling payment pages are crucial for the success of your online business. Adopting smart payout approaches and optimising your payment page can enhance customer satisfaction, boost security, and ultimately increase your revenue. Keep evolving your payment strategies to stay ahead in the ever-changing digital landscape.

Driving Business Growth: 4 Ways Small Businesses Can Utilize Social Media Management Tools

Driving Business Growth: 4 Ways Small Businesses Can Utilize Social Media Management Tools

Starting a business requires support. Business owners are looking for the easiest ways to market their companies. How can a minor firm deal with ROI when it has a limited budget and resources? This is when digital technology becomes a solution. As everyone uses social media platforms daily, it has become a channel for instantly advertising companies. Furthermore, adopting the right social media marketing tools is an excellent approach to making it easy to navigate accounts. These solutions enable users to watch, post, and manage all accounts from a single dashboard.
What is social media management?

Social media management is the method of managing a company's social media activities. It includes providing content and communicating with users. Some businesses manage this informally with staff posting on social media sites. Others hire a social media manager. They handle social media postings and manage social media profiles across several websites. Companies can also employ social media management organizations. They specialize in social media marketing. Social media managers, whether staff or independent contractors are responsible for all parts of social media strategy. They are responsible for idea generation, scheduling, and uploading the material that appears on the platform.

Benefits of managing social media:

Engaging in social media management services might benefit you as a small company owner. You profit in three ways when your staff manages marketing across social media networks:
  1. You contact customers where they spend most of their time. Engaging people on social media networks can help you reach more customers because that is where they spend most of their time.
  2. You educate those who are willing to know about your items. Some customers use social media to investigate a product, while others purchase directly through a social media site. Some of these customers may not bother visiting your website to learn more about your company. You may gain from teaching them through social media.
  3. You discover what the general people are thinking. You understand market trends and can watch user-generated material from your target demographic. You may also track reactions to your social media efforts to determine what the public thinks about your products and services.
Top four ways small businesses can use social media tools:

Now let's look into four ways small businesses can use social media management tools to boost their business and profits.


1. Increase your search engine ranking:

Social networking can help your search engine ranking. When your website's social media sharing rate rises, so does its domain authority. This improves the search engine rating of your sites. But it goes beyond that and many customers will check your social media pages before visiting your website. In this way, they can better understand your business before making a purchase. More visits to social media profiles will ultimately improve their rating and chances of being among the top-rated sites.

2. Drive traffic:

Small companies generally use social media to drive customers to their websites. You will get organic visitors if you have a solid social media presence. It means your traffic consists of the same small group of individuals already following you. Moreover, you must broaden your brand's reach to attract more traffic. So, how do you drive traffic? What is the most efficient method? Create an appropriate social media profile for your small company on each social media network. Then, capitalize on these platforms by distributing customized content to each. A solid social media presence may motivate your fans to follow you through your lead funnel. It would finally lead to your product purchase page. Second, make it easy for people to share your material by showing off social sharing icons on your website. You may also include a Click to Tweet option on a catchy statistic, statement, or other pieces of information to make it more shareable. Moreover, readers can share your articles with a single click.

3. Keep an eye on competitors:

Social media is an excellent method to watch your competition. It allows you to observe and gain inspiration from their performance. You can observe what kind of stuff they post and how they connect with their fans. You may also learn from your competitors by using social media. There must be a simple reason why your competitors are outperforming you. Learn their methods, but do more than copy and paste them. What works best for them may work better for you, instead of modifying their concepts and make them your own. In addition, competitive analysis on social media is all about learning from your competitors. Conducting a self-analysis to determine where you are with your competitors is beneficial. You may undertake competition analysis using a variety of tools. The technology you use should fit the unique needs of your marketing team. Before you select which tool to use, see if the firm has a free trial period.

4. Build brand recognition:

Raising awareness should be a primary priority for any small business. This is usually the case since we know that consumers like to buy from familiar brands. However, this is where social media comes into play. Compared to conventional media, social media can bring your brand in front of your target audience more quickly and easily. Furthermore, it makes your target audience consider your organization. So, make an effort to create and share relevant information. Create cover pictures and user profile photographs on social media networks. Moreover, you can place your brand strategically to have a long-lasting effect on your customer. But don't put your brand anywhere that will be intrusive or overbearing, and remember to pay attention to your brand's aesthetic aspects.

Note: Apart from these things, paying attention to digitizing your business using tools is vital. For instance, many payroll management software offers paystub templates to understand functions before making a final purchase.

The bottom line:

Social media marketing (SMM) uses social media platforms to communicate with customers. It helps to establish brands and drive website traffic. As social media use develops worldwide on computers & mobile devices, the potential to generate revenue is a booming business with fierce competition for views and clicks.


10 Things Investors Need to Consider When the Market is at All-time High

10 Things Investors Need to Consider When the Market is at All-time High

BSE Sensex 30 increased by 10% in the past three months. Similarly, the Nifty 50 index, which represents a broader range of 50 companies, surged by 11% during the same period.

The combined market value of all listed companies on the BSE grew by Rs 1.73 lakh crore to reach Rs 298.21 lakh crore.

The overall market trend has favored the bulls, as around 1,971 stocks gained value, 1,721 stocks declined, and 148 remained unchanged on the BSE.

Investors' confidence is bolstered by encouraging domestic data and positive signals from the global market. The global economy has shown resilience, backed by strong economic indicators, reducing the chances of a recession.

But, long term investment or making daily profits through share trading at market highs are challenging. You don’t know whether the bull run continues or you have profit booking coming in.

The article helps you take a holistic view of what can be done when markets are at all-time highs.
 
10 Things Investors Need to Consider When the Market is at All-time High

1. Take profits

Consider selling some of your holdings or trimming positions in stocks or sectors that have experienced significant gains. This allows you to lock in profits and reduce exposure to potential market declines.

It's important to strike a balance between taking profits and staying invested in positions with long-term growth potential.

2. Seek downside protection

Consider investments that can provide downside protection during market declines. Defensive stocks, such as those in consumer staples or utilities, tend to be less affected by economic downturns.

Bonds and gold are also considered traditional safe-haven assets that can help mitigate portfolio losses during market downturns. Alternative assets like real estate or commodities can also offer diversification benefits.

You need to check whether your stock broker offers other investment assets like NCDs, bonds and gold. Investing Expert report catalog various other investment options offered by the top 20 stock brokers in India.

3. Set stop-loss orders

Trade with or adjust stop-loss orders to protect your downside. These orders automatically sell a stock if it reaches a predetermined price, limiting potential losses in case of a market downturn.

Determine an appropriate level for the stop-loss order based on your risk tolerance and the volatility of the specific stock.

4. Monitor market indicators

Pay attention to market indicators that can provide insights into the overall market conditions.

Look at metrics such as price-to-earnings ratios, market breadth (the number of stocks participating in the market rally), and technical indicators like moving averages or relative strength indicators. High valuations or signs of market exhaustion can be signals for caution.

5. Be cautious with new investments

Exercise caution when considering new investments at market highs. Evaluate whether the stocks or sectors you are interested in are already overvalued relative to their growth prospects.

Consider conducting thorough research, analyzing financial statements, and assessing future earnings potential before making new investment decisions.

6. Review risk tolerance

Reassess your risk tolerance and ensure that your portfolio aligns with your comfort level. Evaluate whether your portfolio is appropriately diversified and if your asset allocation reflects your risk appetite.

As the market reaches its peak, you may want to reduce exposure to more volatile or risky investments and shift towards more defensive or stable assets.

7. Stay disciplined

Emphasize the importance of sticking to your investment plan and avoiding emotional or impulsive decisions based solely on market highs.

Remind yourself of your long-term investment goals and the rationale behind your portfolio allocations. Maintain a disciplined approach and avoid trying to time the market, as it can be challenging to accurately predict market movements.

8. Stay diversified

Maintain a well-diversified portfolio across different asset classes, sectors, and geographies. Diversification helps spread risk and can mitigate the impact of a market decline on your overall portfolio.

Ensure that your investments are not overly concentrated in a single stock or sector, as this can expose you to undue risk.

9. Stay informed and adapt

Continuously stay informed about market trends, economic data, and geopolitical events that can impact the market. Read financial news, follow reputable sources, and stay updated on company-specific developments.

Be prepared to adapt your investment strategy if market conditions change significantly. Regularly review your portfolio and make adjustments as needed.

10. Consider professional advice

If you are uncertain about your investment decisions or need guidance, consider seeking advice from a financial advisor or professional trader.

They can provide personalized advice based on your specific financial situation, risk tolerance, and investment goals. A professional can help you navigate market highs and tailor your investment strategy to align with your objectives.

Remember, these points are general guidelines, and it's essential to consider your individual circumstances and risk tolerance when making investment decisions. Adapt the strategies to your specific situation and consult with a professional if needed.

Tips for Getting Your Financial Health Back on Track

Life can often throw us unexpected challenges that affect our financial health. If you find yourself struggling to manage your personal finances and repay outstanding debts, it's time to regain control by implementing a few crucial changes. In this article, we will share some essential tips to help you get back on the path to financial stability and success.

Develop a Realistic Budget

Tips for Getting Your Financial Health Back on Track

Before you can start improving your financial situation, it's crucial to have a clear understanding of your current income and expenses. Take some time to thoroughly review your bank statements, credit card bills, and receipts to create a comprehensive list of your monthly expenses. Divide these costs into fixed (rent, mortgage, insurance) and variable (groceries, entertainment, clothing) categories for better organization.

Once you have a detailed view of your finances, build a realistic budget that reflects your current financial situation. Prioritize necessary expenses, like rent, utilities, and food, and find ways to reduce discretionary spending, like dining out, hobbies, and vacations. Make a commitment to adhere to your budget, reassess it regularly, and make any necessary adjustments to maintain a positive financial trajectory.

If you need additional help creating a personalized budget, consider reaching out to a financial counseling service like Citizens Debt Relief. They assist people in developing tailored financial plans to eliminate debt and improve their overall financial well-being.

Invest in Your Future

Another excellent way to get your financial health back on track is to consider investing in yourself by pursuing additional education, certification, or training in your chosen field. Pursuing higher education or professional development can lead to better job opportunities, increased salary potential, and long-term financial growth.

For example, if you're considering a career change to a high-demand field, such as Applied Behavior Analysis (ABA), you can explore ABA masters programs online that allow you to obtain advanced degrees while managing your current job and personal responsibilities.

Address Your Existing Debts

Tips for Getting Your Financial Health Back on Track

To regain your financial health, it's critical to tackle your debts in a systematic and targeted manner. Start by listing all your outstanding debts, including credit cards, student loans, and any personal loans. Next, determine how much you can reasonably allocate toward debt repayment each month while still meeting your basic living expenses.

There are several strategies for repaying debts, including the snowball and avalanche methods. Both involve making extra payments on one debt while maintaining minimum payments on others. The snowball method focuses on paying off smaller debts first, while the avalanche method targets high-interest debts first. Choose one that aligns with your personal preferences, and rigorously commit to an ongoing repayment plan.

If you find yourself overwhelmed by multiple debts, consider seeking professional assistance from credit counseling services or debt consolidation programs like the above-mentioned Citizens Debt Relief service. They offer valuable guidance in reducing interest rates, combining multiple payments, and developing customized debt repayment plans.

Establish an Emergency Fund

Finally, a critical aspect of financial health is having an emergency fund that covers at least three to six months' worth of living expenses. This safety net provides peace of mind and financial stability in times of crisis, such as job loss, illness, or unforeseen household expenses.

Start by setting aside a small portion of your monthly income in a separate savings account. Review your budget to identify ways to save, such as cutting discretionary spending or finding additional sources of income. Gradually increase the size of your emergency fund and monitor its growth over time.

Maintain motivation by setting milestones and celebrating each time you reach a specific goal. Keep in mind that growing an emergency fund is an ongoing process that requires patience and discipline.

Altogether, regaining control of your financial health is a vital step in achieving financial independence and stability. By developing a realistic budget, addressing existing debts, establishing an emergency fund, and investing in your future, you can create a solid foundation for a successful and stress-free financial life.

How to Create an Emergency Fund for the Future

How to Create an Emergency Fund for the Future

Managing your finances and knowing how to make your money go further is crucial, but you never know what’s just around the corner. If you’re struggling to stretch your income to the end of the month and you’re hit with an unprecedented expense like a broken boiler, or an urgent car repair, you may be left wondering how you’re going to pay for it. Thankfully, there are options available to help like same day payday loans so you can have access to cash when you need it - which is particularly helpful if you don’t have an emergency fund.

Creating a pot of cash you can use to cover unprecedented expenses in the future is ideal, and means you can handle what life throws at you without having to worry. Here’s how to create your very own emergency fund for the future.

Think about how much you need

If you’re just starting to save, think about how much you’d like to reach as a minimum amount. Generally, it’s said that when saving for an emergency, you should have at least 3 to 6 months' worth of living expenses saved up. This is going to seem like a huge amount, but don’t be put off. All you need to do is come up with a figure that you can afford to save each month and put your plan into action.

Think about your income and your primary expenses. With the money that you have left over from your income each month, make sure you add an amount to your savings. It doesn’t have to be a huge amount, a small amount is better than nothing and we all have to start somewhere! Thinking about how much you’d like to save, and how much you can afford to save will help you get the ball rolling.

Set goals

Once you’ve worked out how much you can afford to save each month, you can start setting goals for your money. Goals are a great way of staying motivated, and allow you to look back at how far you’ve come. You could write down your goals, in a diary or on your phone as a way of staying on track. Of course, as you start hitting your goals, they will change, so make sure you update them throughout your savings journey. Building up a savings pot doesn’t happen overnight, but achieving your goals will give you a sense of achievement and means you’re more likely to stay on the right path towards financial stability.

Open a savings account

Another great step to take as your money begins to build up. A savings account means you’ll have somewhere to keep your money so that you can see exactly how much you have. Depending on the type of savings account you choose, you can actually make money on your savings too, which is preferable to it simply sitting in your bank account. Do some research to find a savings account that comes with good interest rates - you can do this online, or head to a local bank for some advice. Make sure that it’s easy to access in case of emergencies.

Stay consistent

Remaining consistent is crucial when creating your emergency fund. Unfortunately, your savings pot won’t mount up overnight, which is why you need to remain consistent when it comes to transferring and depositing a portion of your income into it regularly. You can automate a transfer from your current account into your savings so you don’t forget and miss a month. Remaining consistent and motivated means you will be able to watch your savings account grow before your eyes.

Only use it for emergencies

Last but not least, make sure you only use your emergency fund for emergencies! Try not to dip into it as this will hinder your progress. If you find that you need to decrease the amount of money you’re saving to make your income go further, you can adjust your payments, just try and remain consistent throughout the months to see the best results. Be stubborn with yourself, and think about your goals when you’re tempted to take money out.

Best Strategies for Cutting Business Electricity Prices

Best Strategies for Cutting Business Electricity Prices

Making sure you're getting the best deal possible on your business electricity is vital to keeping your business profitable. With energy prices on the rise, it is important to stay ahead of the curve and explore the best strategies for cutting business electricity prices. You could be spending too much on your energy bills, but the good news is that there are many strategies that can help you save money.

Using a cost comparison tool can help you find the most competitive prices for your business electricity. Visit www.utilitybidder.co.uk and compare prices with different suppliers.

From negotiating better contracts to taking advantage of government incentives, there are plenty of options for cutting business electricity prices. In this blog post, we'll explore the best strategies for reducing your business energy costs, so you can keep your business profitable and competitive.

Monitor Energy Usage and Establish a Baseline

The first step in cutting business electricity prices is to monitor energy usage and set a baseline. This is essential to ensure that your company is getting the most out of its energy resources. It also allows you to accurately track your electricity usage and identify areas where you may be able to make significant savings. By monitoring energy usage, you can set realistic targets and develop a plan to reduce your electricity bills.

Identify Cost-Saving Potential Through Energy Audits

Energy audits are an effective way to identify potential cost savings through energy efficiency. A thorough analysis of your energy usage, which includes factors such as your daily energy consumption, can provide you with a detailed understanding of where you are currently using energy and how you can save money in the future.

Energy auditors use a range of techniques, such as conducting equipment testing and building inspections, to find potential areas of improvement. Additionally, they can provide advice on how to make those improvements, such as switching to more efficient lightbulbs or installing a programmable thermostat to better manage energy usage. By taking these steps, you can ensure that your business operates in the most cost-effective and energy-efficient way possible.

Negotiate Better Terms With Existing Providers

Negotiating better terms with existing providers is a great way to cut business electricity prices. To do this, businesses should take the time to thoroughly understand their current electricity contract and look for areas where they can save. This includes researching the market to make sure they are getting the best possible deal, studying the terms of the agreement to make sure they are getting the best rates and terms, and determining whether they are able to take advantage of discounts or incentives. By negotiating better terms with their current provider, businesses can ensure they are getting the best deals and prices available.

Seek Out Competitive Quotes From Multiple Suppliers

It is important to remember that when it comes to electricity prices, a competitive market exists. As such, seeking out competitive quotes from multiple suppliers is an important strategy for cutting business electricity prices. By comparing quotes from different suppliers, businesses can get the best possible rate for their electricity.

In addition, suppliers may be willing to negotiate the terms of their offer, such as discounts for bulk purchases or longer contracts. Businesses should take the time to compare quotes and negotiate to ensure they get the best deal possible.

Consider Purchasing Green Energy

To further reduce electricity prices, businesses should consider purchasing green energy. Green energy is energy generated from renewable and non-polluting sources such as wind, solar, and hydropower. By buying green energy, businesses can save money, reduce their carbon footprint, and gain access to renewable sources of electricity.

Additionally, many energy suppliers offer discounts and incentives for businesses that purchase green energy. Businesses should consider researching their options to determine the best green energy option for their needs.

Explore Energy-Saving Options Such as LED Lighting

To effectively reduce the electricity costs of your business, one of the strategies you should explore is the use of energy-saving options such as LED lighting. LED lighting is far more efficient than traditional lighting sources and can potentially reduce your business's electricity consumption by up to 80%.

Furthermore, LED lighting is also much more cost-effective in the long run, as they require significantly less maintenance and replacement over time. Utilizing LED lighting can help your business reduce electricity costs while simultaneously improving the quality of light in your facility.

Take Advantage of Renewable Energy Sources

Taking advantage of renewable energy sources is one of the best strategies for cutting business electricity prices. By switching to renewable sources like wind, solar, and hydropower, businesses can benefit from long-term savings by reducing the need for electricity from traditional sources. Furthermore, businesses can save money from renewable energy credits or other incentives, depending on their geographic location.

Additionally, businesses may be able to tap into local renewable energy grids or collaborate with other businesses to purchase renewable energy in bulk. For businesses looking to cut back on electricity prices, taking advantage of renewable energy sources is an effective way to do so.

Utilize Automated Systems to Monitor and Manage Energy Consumption

Automated systems can be deployed to monitor and manage energy consumption. By leveraging advanced analytics, these systems can provide real-time data on usage, allowing businesses to adjust their power demands accordingly in order to save money.

Automated systems can also be used to detect and resolve problems quickly, preventing spikes in electricity costs. Additionally, automated systems can be used to set and maintain schedules, ensuring that machines are not left running unnecessarily and helping to further reduce energy consumption.
Conclusion

Reducing business electricity prices is an important goal for any organization. By leveraging strategies such as purchasing green energy, exploring energy-saving options like LED lighting, taking advantage of renewable energy sources, and utilizing automated systems to monitor and manage energy consumption, businesses can take steps toward reducing their electric bills while promoting sustainability. With the right approach, businesses can save money while simultaneously helping the environment.

Market Reports

Market Report & Surveys
IndianWeb2.com © all rights reserved